You’ve found the home, and the next step is to get a loan, but wait! You find out that the bank won’t lend you enough to make the purchase.
It’s more common than you think. A couple earns a decent income, falls for a three-bedroom HDB flat or condo, and learns the bank will lend less than what they need for a successful purchase. What a snag to hit.
Fret not. The good news is that there’s a legitimate way to show the bank you’re more than your monthly pay, which is your savings. It’s called pledging and unpledging. In this blog post, I’ll explain both in plain words, with easy-to-understand numbers.
Why Your Home Loan Gets Stuck
Banks in Singapore can’t lend you whatever you ask for. They follow a rule called the Total Debt Servicing Ratio (TDSR). In plain words, no more than 55% of your gross monthly income can go towards repaying all your debts, including the new home loan. “Gross” simply means before tax.
For illustration, say you earn $10,000 a month, and 55% is $5,500. Assuming your car loan and other commitments take another $1,000, the new home loan’s monthly repayment must fit into the remaining $4,500 you are allowed.
There’s a second catch. The bank doesn’t work out your repayment using today’s interest rate. It tests the loan at a higher “safety” rate of at least 4%, in case rates rise later. So the repayment on paper can look bigger than the one you’d really pay.
The result is that if your income is a little short, the loan shrinks, even though you could afford the home in real life.
The Way Out: Let Your Savings Count
If your income alone doesn’t qualify, banks may count some of your savings as additional monthly income. The bank takes the value of your savings, spreads it over 48 months (four years), and adds that monthly amount to your income for the calculation.
Think of a lump sum spread over time. For example, if you have S$48,000, spread over 48 months, this makes it S$1,000 a month that’s counted as additional income.
But how much of your savings counts depends on whether you pledge or unpledge them. The part the bank ignores is called a haircut. (Yes, it’s really called a haircut.)
Pledging: Leave a Deposit
Think about renting a car. You leave a deposit, and the company hands over the keys happily, because it’s holding something of yours.
Pledging works the same way. You lock your money with the lending bank for at least four years. Because the bank is holding it, more of it counts. For Singapore-dollar cash and deposits, the minimum haircut is 0%, so up to all of it can count.
Like in the earlier example, say you need an extra S$1,000 a month of recognised income to qualify. Pledge S$48,000 (S$1,000 × 48 months), and the bank counts all of it.
You can also pledge other assets, such as shares, bonds, unit trusts or gold, if your bank accepts them. These take at least a 30% haircut, so at most 70% counts.
Unpledging: Show, Don’t Hand Over
Now think about renting a flat, or getting a visa to another country. The landlord or governing authorities might ask to see your bank statement to prove you can sustain yourself.
Unpledging, also called “show cash”, works like that. You show the bank your savings as proof, once when you apply and again just before the loan is paid out. Your money isn’t locked, so you can use it afterwards.
The catch is that the bank can’t hold your money, so it trusts it less. The minimum haircut is 70%, so at most 30% counts.
The same example: to get S$1,000 a month of recognised income, you’d need to show S$160,000 (S$1,000 × 48 ÷ 0.3). That’s more than three times the pledged amount.
Two rules to remember. The bank checks that the money is still in your account just before it pays out the loan, and money you’re using for the down payment can’t be counted.
Pledging vs Unpledging at a Glance
| Pledging | Unpledging (“show cash”) | |
|---|---|---|
| What you do | Lock the money with the lending bank | Show the money in your accounts |
| Time involved | At least 4 years (48 months) | None, but the money must stay put until the loan is paid out |
| Singapore-dollar cash that counts | Up to all of it (minimum haircut 0%) | At most 30% (minimum haircut 70%) |
| Shares, bonds, unit trusts, gold that count | At most 70% (minimum haircut 30%) | At most 30% (minimum haircut 70%) |
| Cash needed for S$1,000 a month of income | S$48,000 | S$160,000 |
| Can you use the money? | No, it’s locked | Yes, after the loan is paid out |
| Think of it as | A car-rental deposit | Showing a landlord your bank statement |
Pledging in Action: Sally’s S$1.7 Million Home
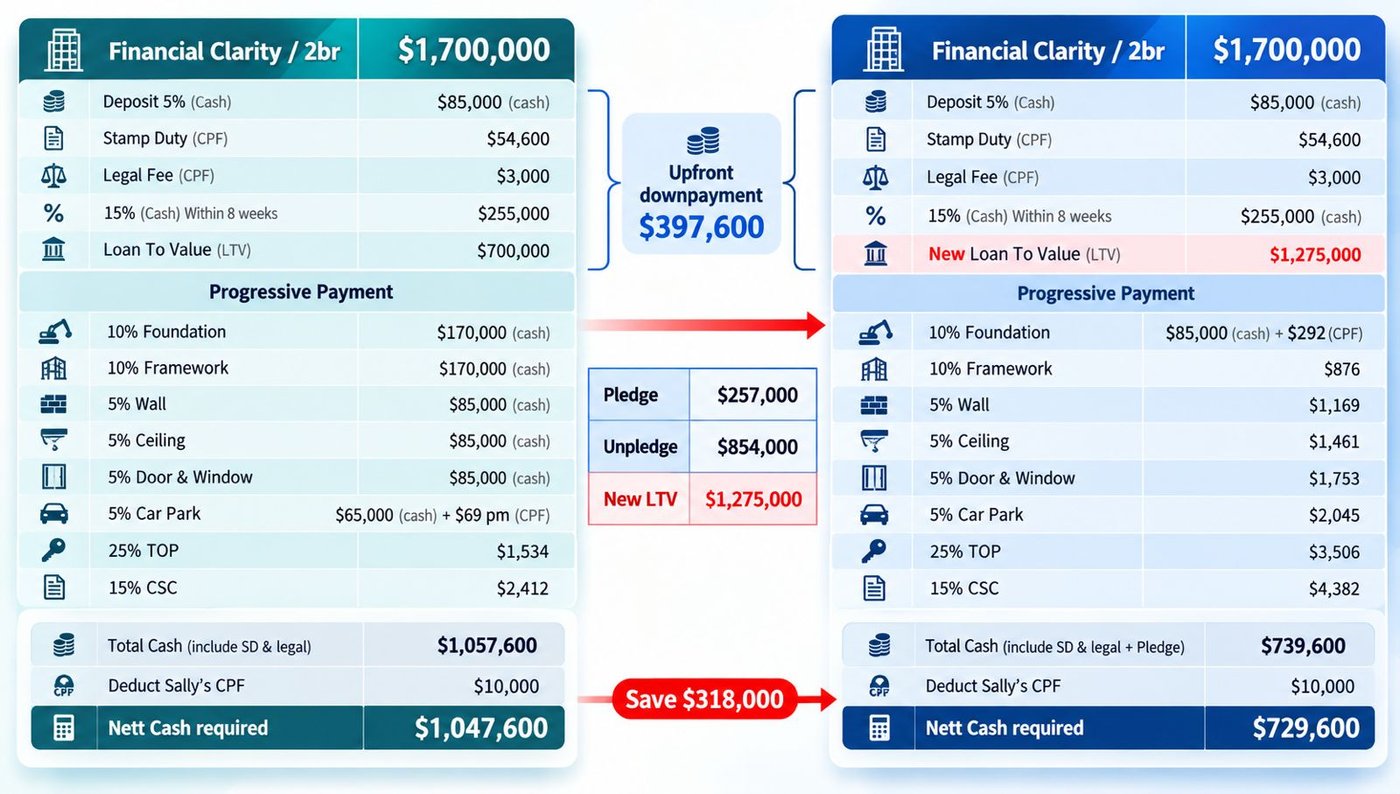
Sally, a 25-year-old client, wanted to buy a three-bedroom condominium at S$1.7 million. She decided to use cash reserves borrowed from her parents, and she looked at both options:
- Option 1 (Pledging): pledge S$257,000 to the bank as collateral for four years.
- Option 2 (Unpledging): show S$854,000 to the bank, both when she applied and when the loan was paid out.
Notice the sizes. The unpledged amount is about 3.3 times the pledged one, because 30% of S$854,000 is roughly S$257,000.
Either way, she bought the S$1.7 million home. Her cash payment dropped from S$1,047,600 to S$729,600, about 30% less upfront cash.
One More Example: Cash vs Shares
For illustration only, say Jia Wei has S$100,000 and wants to see how it counts. Divide each by 48 months:
- Pledged cash: S$100,000 ÷ 48 = about S$2,083 a month of recognised income.
- Pledged shares (if the bank accepts them): at most 70% × S$100,000 ÷ 48 = about S$1,458 a month.
- Unpledged, either kind: at most 30% × S$100,000 ÷ 48 = about S$625 a month.
Same S$100,000, three very different results. The type of asset and the way you use it both matter.
Which Option Suits You?
- Pledge if you have enough cash that you won’t need for four years.
- Unpledge if you want your money free to use, and you have plenty to show.
- Neither if your income already qualifies for the bank loan you need.
- Wait if either option would leave you with no breathing room. Building up your reserves first is often the smarter move.
The Fine Print
- Four years is non-negotiable. An asset pledged for less than that is treated as unpledged.
- These are minimums. Each bank can be stricter in deciding which assets it will accept. MAS expects loans to stay within the 55% cap, with only exceptional cases allowed above it.
- Pledged money is locked. Don’t pledge your emergency fund. Make sure you 100% won’t need it.
Cutting the Long Story Short
- Pledging is like leaving a deposit: you need less money, but it’s locked for four years.
- Unpledging is like showing your bank statement: your money stays free, but you need a lot more of it.
- Both are ways of telling the bank, “I can afford this, and here’s the proof.”
Next Steps?
If you’re wondering which option suits your situation, or whether you need either, send me your numbers. We’ll work through it together before you make your move.
No pressure, no rush, and if the answer is “not yet”, I’ll tell you that too.